
A Canadian EB-5: How to End the Recession Without Spending a Dollar
Canada has a supply problem it is not going to spend its way out of — and the fix may be a Canadian EB-5: an investor-immigration program that puts private capital to work building the homes the country can’t finance on its own. Here is the case, and the blueprint.
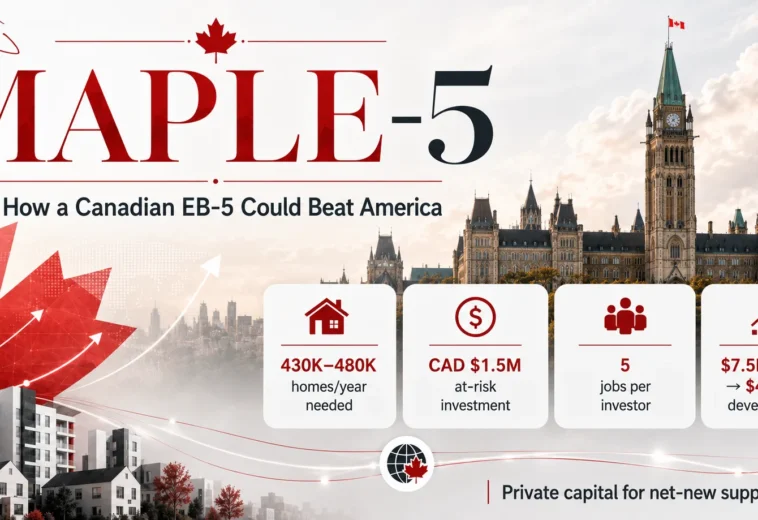
The math is brutal and it comes straight from CMHC. To restore affordability by 2035, Canada needs between 430,000 and 480,000 new housing units every single year — up to 4.8 million homes over the decade. In 2025 the country started roughly 259,000. Even Alberta, which broke a 70-year record with about 54,000 starts (nearly a quarter of the national total, from under 12% of the population), is running at half the pace the country needs.
And the public purse is already stretched. In 2025 alone CMHC deployed $29 billion through the Apartment Construction Loan Program and $14 billion through the Affordable Housing Fund. Necessary — but a fraction of the gap. The agency itself is now openly looking to connect projects to private capital.
So here is the real question. There is a global pool of investors willing to put seven figures into a country in exchange for residency. Canada is currently capturing almost none of it — and the little it does capture, it wastes.
The program Canada already killed
Canada is not new to investor immigration. It ran a federal Immigrant Investor Program for years and shut it down in 2014. The reason is the whole lesson: investors weren’t maintaining real ties to the country, and they paid far less tax than other economic immigrants. Quebec kept its own version and then suspended it too, after discovering that 85% of its investor immigrants ended up in Ontario or B.C. — and only 10% stayed.
Two failures, and both are fixable: passive capital (essentially a loan to government that built nothing and created no jobs), and no roots (money came in; people didn’t). Meanwhile, the United States took the opposite approach — and it works.
What the US gets right
The American EB-5 program doesn’t lend money to the state. It forces the investor to put capital at risk in a business that creates jobs. The current thresholds are USD $800,000 in a Targeted Employment Area and $1.05 million elsewhere, and each investor must generate at least 10 jobs. In fiscal 2024 the US issued a record 12,055 EB-5 visas. The capital overwhelmingly finances one sector: real estate and construction, where developers use it as low-cost gap equity.
The critical design feature people miss: EB-5 doesn’t let the market decide where the money lands. The state pre-approves which projects and zones qualify. Government holds the map. That single mechanism solves the concentration problem that sank Quebec’s program.
The blueprint: a Canadian EB-5 called Maple-5
Canada doesn’t need to invent anything. It needs to copy the good version and fix it for its own reality. A Canadian EB-5 would rest on six rules:
- Investment. CAD $1.5 million, at risk (equity, not a loan), locked for a minimum of five years, deployed only into state-approved real estate development.
- What it can fund. Net-new supply only — new housing, multifamily, densification, adaptive reuse, industrial and logistics. Never the purchase of existing stock. You add homes; you don’t bid up the ones already standing.
- Jobs. A minimum of 5 jobs per investor (direct plus indirect). Ten, as in the US, isn’t realistic in today’s Canadian labour market. Five is.
- No parking the money. Residency comes with immediate tax residency and worldwide taxation from day one, plus a minimum physical-presence requirement — killing the 2014 failure at the root.
- The state picks the map. Ottawa and the provinces designate eligible zones and projects, with lower thresholds in priority areas — housing-shortage markets, rural communities, target sectors.
- Integrity by design. Funds held in escrow, released against construction milestones, with independent audits — the guardrails the US added with its 2022 Reform and Integrity Act.
The competitive angle nobody is naming
The common objection is that worldwide taxation will scare investors off. It won’t — and understanding why is the whole opportunity. The United States already taxes on worldwide income. Every EB-5 green-card holder is subject to it. The pool of investors doing US EB-5 today has already accepted that deal. A Canadian EB-5 asking for the same thing isn’t a disadvantage — it’s direct competition for the exact same clientele.
And Canada can offer a better version. US worldwide tax is chained to the passport; leave and you still pay, with an exit tax on the way out. Canadian tax residency ends when you actually leave. Same terms on entry, far less of a life sentence. Better still, American EB-5 capital pours into California and New York — worldwide tax plus the highest state taxes in the country. Route a Canadian EB-5 through Alberta and you get worldwide taxation in the lowest-tax province in Canada: no provincial sales tax, among the lightest personal rates in the country.
Same entry deal as a US green card. Lower tax. No lifetime chain. This isn’t “bringing money in instead of handing it to America.” It’s taking it from America.
The predictions
Assume a deliberately modest program — CAD $1.5M per investor, 5 jobs each:
- 3,000 investors/year → $4.5B in private equity into net-new development, ~15,000 jobs
- 5,000 investors/year → $7.5B, ~25,000 jobs
- 8,000 investors/year → $12B, ~40,000 jobs
At-risk equity typically unlocks several times its value in total project financing. At the mid scenario, $7.5B of equity could catalyze $40–50B in development annually — a serious dent in a national build target of 430,000–480,000 homes a year. And it pays twice: unlike the 2014 program, every investor is now a worldwide-taxed resident — recurring revenue, not a one-time cheque.
And the recession Canada is in right now?
This isn’t abstract. In the first quarter of 2026, Canada slipped into a technical recession — two straight quarters of contraction (−1% annualized in Q4 2025, −0.1% in Q1 2026). The causes Statistics Canada listed are almost on the nose: business investment falling for a fifth consecutive quarter, and weak residential construction dragging on growth. Those are the exact two levers a Canadian EB-5 pulls.
Let me be honest about timing. A program like this needs 12 to 18 months to legislate and ramp. It won’t be what ends this particular downturn — a shallow one forecasters already expect to lift by late 2026. The case is what comes after. On a roughly $3.3-trillion economy, a program catalyzing $40–50 billion a year of net-new development — around 1.2 to 1.5% of GDP, concentrated in the weakest sector — could add an estimated 0.5 to 1.0 percentage point to annual growth once at scale. In quarters like the two Canada just posted, where the whole economy swung on a fraction of a point, that is the difference between contraction and expansion.
Realistic timeline: a measurable GDP contribution within 18 to 24 months of launch, material within two to three years — and a structural floor under the one sector that keeps pulling the country toward recession every time a trade shock lands. A stimulus that costs the treasury nothing and pays itself back in tax.
The demand is already there. European interest in Canada today is nothing like it was in 2014. What’s missing isn’t appetite. It’s the channel. Canada killed its investor visa once. The version that replaces it shouldn’t sell residency — it should build the homes the country can’t finance on its own.
Working on a development or feasibility project that fits this thesis? Let’s talk.
This is a policy proposal and thought experiment — Maple-5 is not an existing program. Figures on the housing gap and 2025 housing starts (CMHC), Canada’s Q4 2025 / Q1 2026 technical recession and ~$3.3-trillion GDP (Statistics Canada), the former Immigrant Investor Program and Quebec’s QIIP, US EB-5 thresholds and FY2024 visa volumes, and Alberta’s tax position are drawn from public sources. The investment, job, capital and GDP-contribution projections are illustrative scenarios based on stated assumptions, not forecasts.
- 100 views
- 0 Comment

Eros Belotti 01.

Eros belotti
Construction project manager with over 20 years of experience in Europe and the Canary Islands. Specialized in modular housing, container construction, real estate development and international project management. Founder of Reforma Vivienda Tenerife and Donkey Lab.