
//Alberta Non-Residential Construction: The 2026 Shift to Watch
Alberta Non-Residential Construction: The 2026 Shift to Watch
Tags : AlbertaBuildForceconstruction marketFeasibilitynon-residential constructionreal estate investment
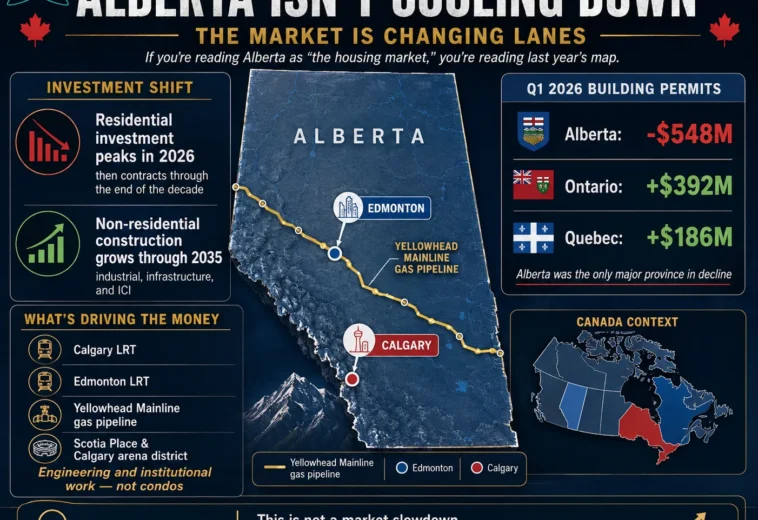
Alberta non-residential construction is quietly becoming the most important story in the province’s building sector — and it’s the one most people are still missing. While headlines fixate on housing, the data shows the money changing lanes: residential investment is set to peak in 2026, while non-residential activity keeps climbing through 2035. For any company weighing an Alberta entry, reading the province as “the housing market” means reading last year’s map.
Here is what the numbers actually say, and what the shift means if you plan, finance, or build projects in the province.
Residential construction in Alberta peaks in 2026
Alberta remains one of Canada’s stronger residential markets per capita, but momentum is cooling. As of March 2026, annualized housing starts sat at 46,064 units — down 5% year over year. The two major metros tell the same story:
- Calgary: 24,023 annualized starts (down 4% YoY)
- Edmonton: 17,217 annualized starts (down 8% YoY)
The one bright spot is rental: purpose-built rental starts hit record highs in both Calgary and Edmonton, partly offsetting a sharp contraction in condominium activity. According to CMHC data, residential investment is forecast to reach its peak in 2026 before receding, as slower population growth outweighs modest renovation gains. In short: the residential wave isn’t crashing — it’s cresting.
Where Alberta non-residential construction is heading through 2035
This is where the picture flips. Alberta non-residential construction — industrial, institutional, commercial (ICI) and engineering work — is projected to grow almost continuously through 2035, offsetting the moderation in housing. BuildForce Canada forecasts sustained high levels of non-residential activity across the decade, with both engineering and ICI buildings contributing to the expansion.
The labour data underlines how real this demand is. Alberta’s construction workforce will need to add 48,800 workers by 2035, driven largely by 43,700 expected retirements — roughly 21% of the 2025 labour force. Even accounting for immigration, the province could face a residual recruiting gap of around 15,400 workers by 2034. Growth this durable doesn’t come from a soft market.
The Q1 2026 permit signal most people misread
In the first quarter of 2026, Alberta was the only major province where the value of building permits fell — down $548 million — while Ontario (+$392 million) and Quebec (+$186 million) climbed, per Statistics Canada.
On the surface that reads like weakness. Read alongside the forecasts, it reads like rotation: residential intentions pulling back as the sector approaches its peak, while the heavier, longer-cycle non-residential pipeline builds. A single quarter of permit values is a snapshot, not a trend — and mistaking the two is exactly how firms misprice an entry.
What’s actually driving the growth
The expansion in Alberta non-residential construction isn’t broad-based consumer demand — it’s a defined set of large engines:
- Transit: light rail transit (LRT) expansions in both Calgary and Edmonton
- Energy infrastructure: the Yellowhead Mainline natural gas pipeline and sustained oil, gas and utilities investment
- Institutional and commercial anchors: Scotia Place and Calgary’s arena and Arts Commons district
- Data centres: a provincial ambition to attract $100 billion in data centre investment within five years, headlined by the proposed $70 billion Wonder Valley campus (though construction is not expected to begin until roughly 2028)
A caveat worth naming: growth is concentrated
This is the part optimistic market summaries skip. The non-residential upside is driven by a handful of megaprojects, not by diffuse, organic demand. The data centre numbers in particular are enormous but not yet organic — they hinge on a small number of projects that still face timing, water and power questions.
That concentration is precisely why timing and feasibility matter more than headline optimism. Betting on the sector average will mislead you, because there is no smooth average — there are specific pipelines with specific schedules. Getting the feasibility study, the phasing and the resource plan right is what separates a profitable entry from an expensive one. It’s also where avoidable costs hide: across the industry, rework typically consumes 5–9% of total project cost, and on a $50 million project that’s $2.5 million that disciplined upfront work can protect.
What this means for European firms entering Alberta
For a European construction, real estate or development company evaluating Alberta, the strategic question isn’t “is the market up or down.” It’s “which lane, and when.”
The residential window is late-cycle; entering it now means competing for a peaking market. The non-residential window — industrial, institutional and engineering — is opening and stays open through the decade, but it rewards partners who can read the project pipeline, not the sector headline. Positioning around feasibility, project management discipline and the specific megaproject calendar is how a newcomer earns a seat at that table.
Frequently asked questions
Is Alberta’s construction market slowing down in 2026?
Only in one segment. Residential investment is forecast to peak in 2026 and then soften, but Alberta non-residential construction is projected to grow almost continuously through 2035, keeping overall activity elevated.
Why did Alberta building permits fall in Q1 2026?
Alberta’s permit value dropped $548 million in Q1 2026, largely reflecting cooling residential intentions as that sector nears its peak. It signals a rotation toward non-residential work rather than a broad decline.
What is driving non-residential construction growth in Alberta?
Major engines include Calgary and Edmonton LRT, the Yellowhead Mainline pipeline, institutional projects like Scotia Place, and a $100 billion provincial data centre ambition — a concentrated set of megaprojects rather than broad demand.
I help European and Canadian firms read the Alberta pipeline — from feasibility and surveying to project management. If you’re mapping the same shift, let’s compare notes.
- 143 views
- 1 Comment

Eros Belotti 01.

Eros belotti
Construction project manager with over 20 years of experience in Europe and the Canary Islands. Specialized in modular housing, container construction, real estate development and international project management. Founder of Reforma Vivienda Tenerife and Donkey Lab.
August 12, 2026 /
Author’s note: I wrote this because too many market summaries flatten Alberta into a single “up or down” headline. The real story is the rotation — residential cresting in 2026, non-residential building through 2035 — and it changes how you’d time an entry.
For transparency, every figure here is sourced. If you want to check the numbers yourself:
Housing starts & residential outlook — CMHC: https://www.cmhc-schl.gc.ca/professionals/housing-markets-data-and-research/housing-data/data-tables/housing-market-data/monthly-housing-starts-construction-data-tables
Non-residential forecast & labour demand to 2035 — BuildForce Canada: https://www.buildforce.ca/en/press-release/employment-demands-increase-in-alberta-to-2034-with-growth-greatest-in-the-non-residential-sector/
Q1 2026 building permits by province — Statistics Canada: https://www150.statcan.gc.ca/n1/daily-quotidien/260519/dq260519b-eng.htm
Cost of rework benchmark — CII / PlanRadar: https://www.planradar.com/us/cost-of-rework-construction/
One caveat I’ll repeat: the non-residential upside is concentrated in a handful of megaprojects, not broad demand. Which is exactly why timing and feasibility beat headline optimism. Questions or pushback welcome — happy to dig into any of these numbers.