
- Alberta
- Alberta Construction
- Alberta Economy
- Alberta Real Estate
- Calgary Real Estate
- Canada Construction
- Construction Canada
- Construction Management
- Feasibility
- Housing Starts
- HousingMarket
- New Builds
- Project Management
- Property Development
- Real Estate Canada
- Real Estate Development
- Real Estate Investing
- Urban Development
Calgary Housing Market 2026: Record Supply Meets Slower Sales
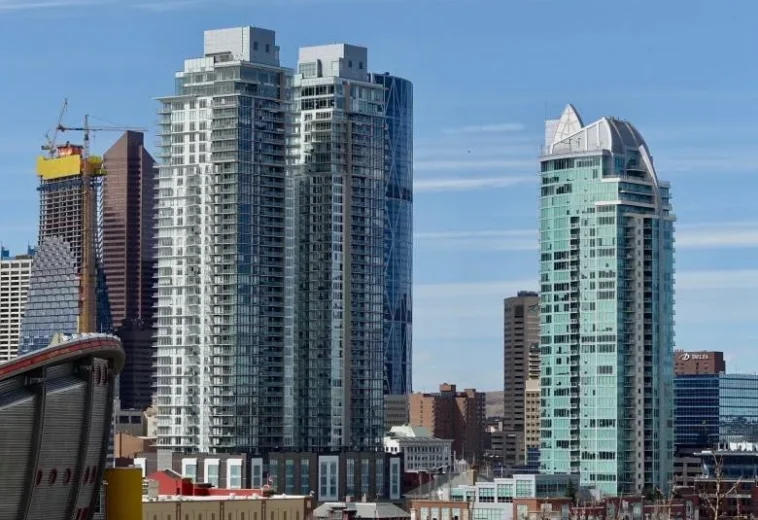
In 2025 Alberta set a new housing starts record. A few months later, Calgary’s resale market was sending a very different signal: fewer sales, more inventory and falling prices in the segments that builders had been adding fastest. Both things are true at the same time, and anyone planning a residential project in Alberta needs to understand why.
This article looks at the March 2026 numbers from the Calgary Real Estate Board (CREB), explains what is happening segment by segment, and sets out what it means for developers, builders and investors deciding what to build next.
The record year: what Alberta built in 2025
According to ATB Financial’s analysis of CMHC data, Alberta recorded 54,858 housing starts in 2025, beating the previous 2006 peak of 48,962. Starts were 15% higher than in 2024 and 33% higher than in 2023, and Alberta accounted for just over 21% of all housing starts in Canada.
The mix matters even more than the total. Multi-unit dwellings made up 70% of 2025 starts, the highest share on record. Roughly 90% of all starts were concentrated in the Calgary and Edmonton metro areas. In other words, the record was built mostly with apartments and attached product, in two cities.
March 2026: what Calgary’s market actually shows
CREB’s March 2026 figures describe a market that has cooled without collapsing:
- Sales: 1,881 residential sales, down 12.8% year over year.
- New listings: 3,409, down 15.2% year over year.
- Inventory: 5,395 active listings, about 5% higher than a year earlier.
- Months of supply: 2.87, up from 2.39 in March 2025.
- Benchmark price: $565,600, down 4.2% year over year but up almost 1% from February.
- Days on market: 35, up from 29 a year earlier.
None of these numbers describe a crash. Months of supply below three still points to a fairly balanced market overall. But the citywide average hides a sharp split between property types.
The segment split: detached holds, apartments absorb the pressure
Breaking the March data down by product type shows where the adjustment is happening:
- Detached: sales down 5.0%, 2.22 months of supply, benchmark price $741,300 (-3.3%).
- Semi-detached: sales up 4.9%, 2.49 months of supply, benchmark $686,100 (-0.9%).
- Row: sales down 19.3%, 2.98 months of supply, benchmark $423,900 (-6.2%).
- Apartment: sales down 28.8%, 4.62 months of supply, benchmark $300,300 (-9.3%).
The segments under the most pressure are exactly the ones where new supply has been concentrated. Apartments now have almost twice the months of supply of detached homes, and their benchmark price has fallen nearly three times as much. Ground-oriented family housing, which is harder and slower to deliver, is holding its value much better.
Why supply outpaced absorption
The explanation is not mysterious. Construction decisions are made 12 to 36 months before units reach the market. In 2023 and 2024 Alberta was absorbing record interprovincial and international migration, and builders responded by launching multi-family projects at scale. ATB notes that Alberta’s population grew 4.7% in 2024, slowed to 2.5% in 2025 and is expected to grow about 1.5% in 2026.
Demand slowed, but projects already underway kept delivering. When completions arrive in a market whose growth rate has halved, inventory builds up in the product types that were launched in volume. That is a timing problem, not a collapse of fundamentals.
What this means for developers and builders
1. Product mix is now a feasibility question, not a marketing one
In 2024 almost any well-located multi-family project could be justified. In 2026 the same land can support very different outcomes depending on whether it is planned as apartments, townhomes or semi-detached units. A feasibility study should test at least two product mixes against current absorption and price data, not against last year’s assumptions.
2. Absorption assumptions need to be stress-tested
Days on market rising from 29 to 35 citywide, and to around 45 for apartments, directly affects carrying costs, interest reserves and sales timelines. Pro formas built on 2024 absorption rates can look viable on paper and still run short of cash during sell-out.
3. Calgary and Edmonton are not one market
Edmonton has a different price level, a different supply pipeline and different investor dynamics. Treating “Alberta” as one market leads to wrong conclusions in both directions. City-level and segment-level data should drive the decision.
4. Cost control matters more when prices stop rising
When benchmark prices fall 4% to 9% in some segments, the margin that used to absorb small overruns disappears. Locked design decisions, complete drawings before tender and documented change control become direct profit protection.
What to watch over the next 12 months
Three indicators will tell developers whether the adjustment is deepening or stabilising. First, apartment months of supply: if it stays above four for several consecutive months, price pressure on new condo launches will continue. Second, new listings versus sales: in March both fell, which limits how quickly inventory can grow. Third, completions from the 2024 and 2025 start cohorts: as these units finish, they add to rental and resale supply in exactly the segments already under pressure. Tracking these monthly, rather than relying on annual headlines, is the simplest way to time a launch or a land purchase.
The bottom line
Alberta’s market is still growing, and starts are expected to remain about a third above the ten-year average in 2026 even after falling from the 2025 peak. But growth no longer makes every project viable. The right question is no longer “is Alberta growing?” but which segment, which city and which timing.
If you are evaluating a residential project in Calgary or elsewhere in Alberta and want an independent read on the feasibility numbers, see my construction project management services or get in touch.
Frequently asked questions
Is Calgary’s housing market crashing in 2026?
No. Citywide months of supply was 2.87 in March 2026, which indicates a broadly balanced market. Prices are adjusting, especially for apartments and row homes, but the data does not show a crash.
Which housing segment is weakest in Calgary?
Apartments. In March 2026 apartment sales fell 28.8% year over year, months of supply reached 4.62 and the benchmark price dropped 9.3%.
How many housing starts did Alberta record in 2025?
54,858, a provincial record and about 21% of all starts in Canada, according to ATB Financial’s analysis of CMHC data.
Sources
- REW: Calgary real estate market analysis, March 2026 (CREB data)
- ATB Financial: Housing starts in Alberta, December 2025
- 377 views
- 0 Comment

Eros Belotti 01.

Eros belotti
Construction project manager with over 20 years of experience in Europe and the Canary Islands. Specialized in modular housing, container construction, real estate development and international project management. Founder of Reforma Vivienda Tenerife and Donkey Lab.