
Calgary Non-Residential Tax Ratio Hits 4.63. Edmonton Is Just Over 3.
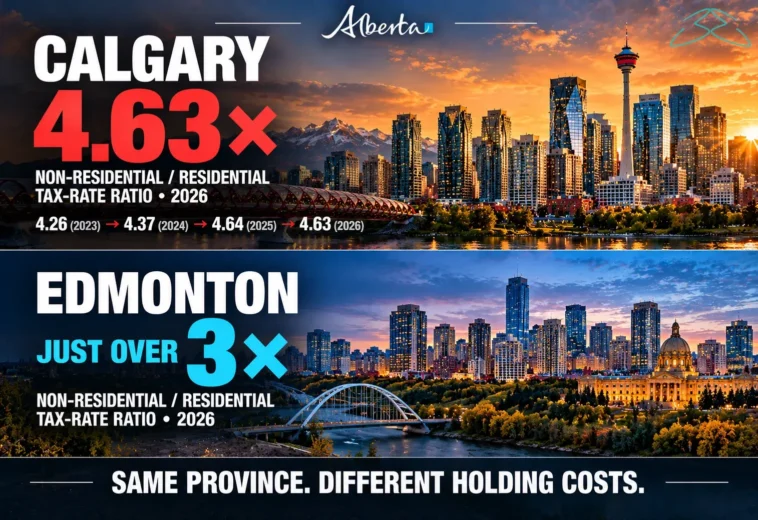
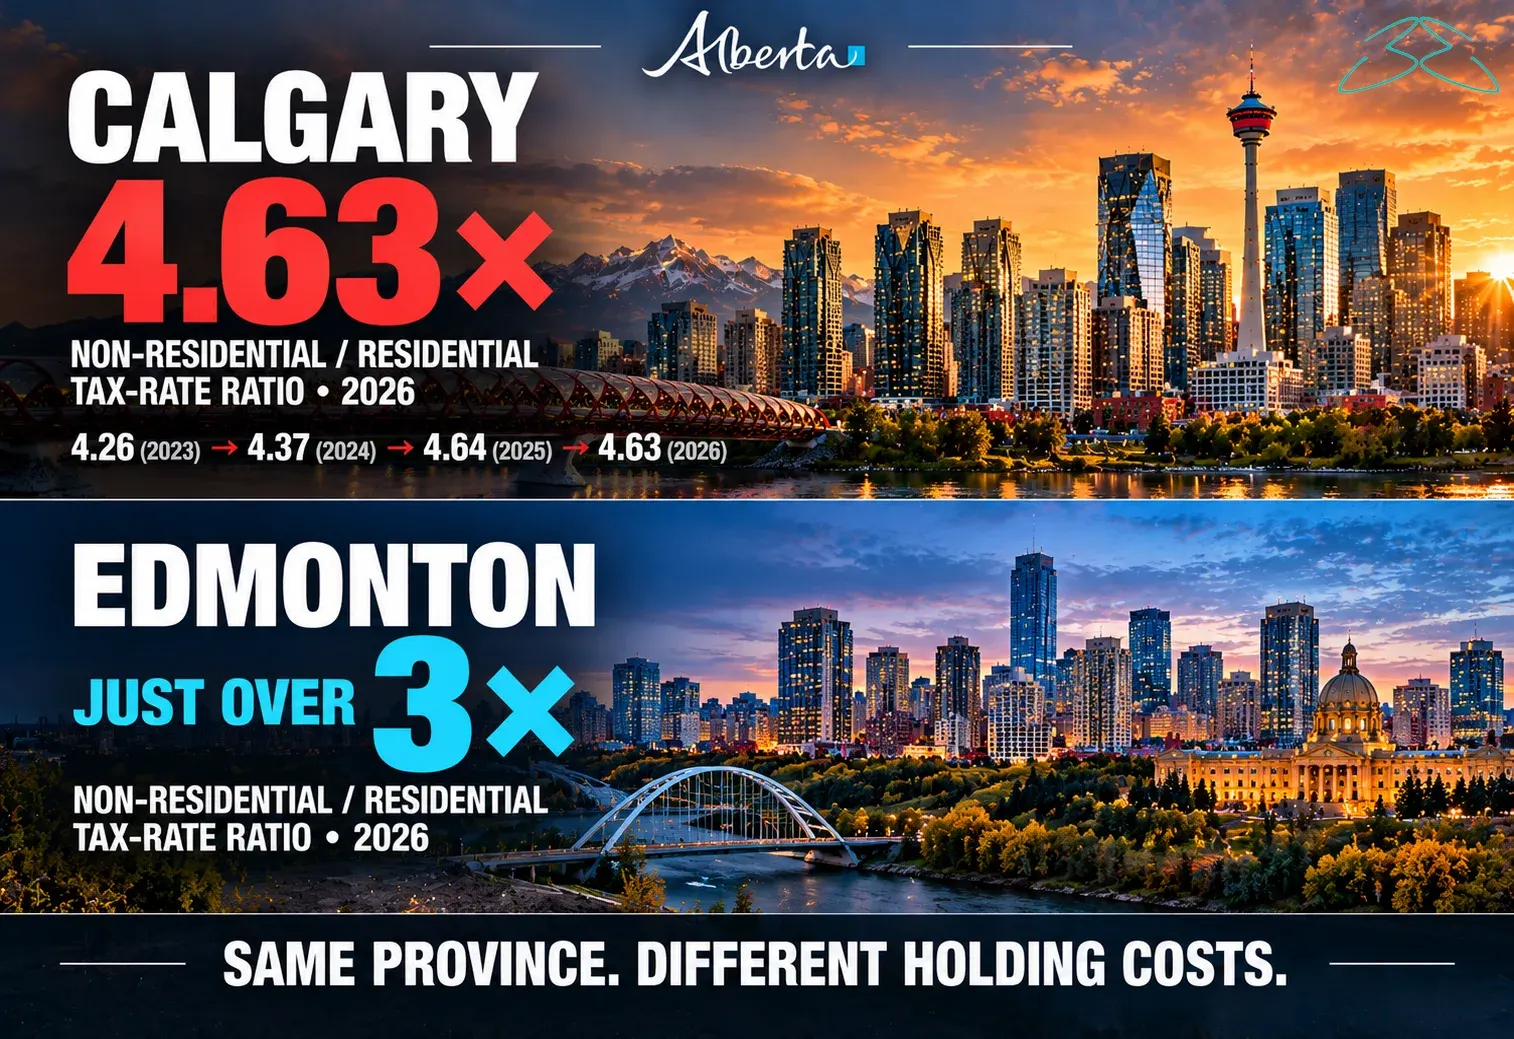
Calgary’s non-residential tax ratio reached 4.63 in 2026. Edmonton’s is just over 3. Same building, same tenant. One city costs considerably more to hold.
In November 2025, Calgary City Council cancelled the 1% shift of the tax burden from businesses to homeowners that had been planned for 2026. The shift was part of a plan approved in November 2023 covering 2024 to 2026. According to the City of Calgary, Council instead approved a much slower shift of 0.25% a year over eight years, starting in 2027.
For developers, owners and investors in commercial real estate, this is not just a municipal politics story. It is a fixed line in every pro forma.
Table of Contents
- What the Non-Residential Tax Ratio Measures
- Calgary’s Ratio from 2023 to 2026
- Calgary vs Edmonton: Share of Taxes vs Share of Value
- How the Tax Shift Worked, and Why It Stopped
- Holding Costs in a Feasibility Study
1. What the Non-Residential Tax Ratio Measures
The non-residential tax ratio compares the municipal property tax rate applied to non-residential property with the rate applied to residential property.
In practical terms: on two properties with the same assessed value, where a homeowner pays $1 in municipal property tax:
- a business in Calgary pays about $4.63;
- a business in Edmonton pays just over $3.
Alberta’s legal cap on this ratio, set in 2016, is 5 to 1. Calgary is approaching it.
2. Calgary’s Ratio from 2023 to 2026
Calgary’s non-residential tax ratio has moved as follows:
- 2023: 4.26
- 2024: 4.37
- 2025: 4.64
- 2026: 4.63
This happened during the same period in which the business share of property taxes fell from 48% to 45%.
How can both be true? The share of taxes depends on assessed values as well as rates. When residential values rise faster than non-residential values, more of the tax burden falls on homeowners even if rates stay the same. To keep shifting the burden in a particular direction, the city has to adjust the rates. In Calgary’s case, the rate ratio kept rising.
The share of taxes improved for business. The rate gap did not.
3. Calgary vs Edmonton: Share of Taxes vs Share of Value
The Canadian Federation of Independent Business (CFIB) compares the share of property taxes that businesses pay with their share of the assessed value:
- Calgary: businesses pay 46% of property taxes with 15% of the assessed value (CFIB, Calgary).
- Edmonton: businesses pay 45% of property taxes with 22% of the property value (CFIB, Edmonton).
CFIB is a business advocacy group, so its framing reflects that perspective. But the underlying comparison is clear: in both cities, businesses carry a far larger share of the tax bill than their share of property value, and the gap is wider in Calgary.
4. How the Tax Shift Worked, and Why It Stopped
Moving 1% of the tax burden from non-residential to residential meant roughly 2% more tax for homeowners and roughly 2% less for businesses, each year. It did not change the total the city collects, only who pays it.
Council cancelled the 2026 step in response to economic pressures on households. The replacement plan, from 2027, shifts 0.25% a year over eight years.
For a business owner today, real relief is a long way off. A project being underwritten now, with a hold period of five to ten years, will carry most of its life under a ratio close to today’s.
For broader context on how property tax has moved in Calgary, see Calgary Property Tax 2026: The City Raised 1.8%. The Province Raised 21%.
5. Holding Costs in a Feasibility Study
The issue is not what it costs to build. It is what it costs to hold.
In a feasibility study, property tax is not a footnote. It is a fixed operating cost that:
- Changes with the city, not with the project. The same building pays different taxes depending on the municipality.
- Affects net operating income. Under net leases, tenants pay it and it affects their willingness to pay rent. On vacant space, the owner pays it directly.
- Affects value. Lower NOI at the same cap rate means a lower valuation.
- Applies during lease-up. Holding costs on vacant or partially leased space hit the developer before stabilisation.
A practical approach when comparing Alberta locations for a commercial project:
- Model taxes by municipality, using the current non-residential rate, not a provincial average.
- Project the ratio forward, including announced shifts such as Calgary’s 0.25% per year from 2027.
- Compare total occupancy cost, not just rent, for tenants deciding between cities.
- Include satellite cities. Municipalities such as Airdrie, Cochrane and Okotoks have their own rates and growth dynamics, as covered in Calgary’s Housing Supply Gap.
- Add one-time costs too. Development charges also differ widely by city: see Development Charges by City: The Full Canadian Ranking.
Same Province, Different Holding Costs
Calgary’s non-residential tax ratio of 4.63 is among the highest in Canada and close to Alberta’s legal cap. Edmonton’s is just over 3. The planned relief in Calgary has been slowed to 0.25% a year from 2027.
For the same commercial project, that difference sits in the pro forma for the entire hold period.
For your next commercial project: Calgary, Edmonton, or a satellite city like Airdrie, Cochrane or Okotoks?
Sources: City of Calgary, property tax and tax share information; CFIB statements on the Calgary and Edmonton 2026 budgets.
- 6 views
- 0 Comment

Eros Belotti 01.

Eros belotti
Construction project manager with over 20 years of experience in Europe and the Canary Islands. Specialized in modular housing, container construction, real estate development and international project management. Founder of Reforma Vivienda Tenerife and Donkey Lab.