
- Alberta Construction
- Alberta Economy
- Alberta Real Estate
- Calgary Construction
- Calgary Real Estate
- Canada Construction
- Construction Management
- Feasibility
- Housing Starts
- HousingMarket
- New Builds
- Project Management
- Property Development
- Real Estate Canada
- Real Estate Development
- Real Estate Investing
- Urban Development
Alberta Broke Every Construction Record in 2025. Records Are Not a Strategy
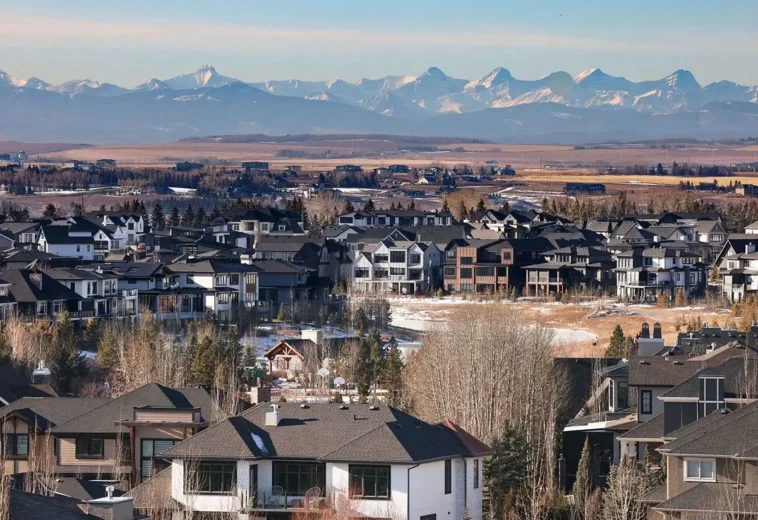
2025 was the biggest year for housing construction in Alberta’s history. The province recorded 54,858 housing starts, beating the previous record set in 2006, and both Calgary and Edmonton posted record annual totals. Yet by early 2026 the conversation had changed: resale activity slowed, inventory rose in the condo segment and forecasters expected starts to fall by about 10,000 units.
The lesson for developers, builders and investors is simple to state and hard to apply: a record year is a result, not a strategy. This article explains what the 2025 numbers really show and how to use them when deciding what, where and when to build in Alberta.
The 2025 numbers in context
According to ATB Financial’s review of CMHC data, Alberta’s 54,858 starts in 2025 were 15% higher than 2024 and 33% higher than 2023. Alberta accounted for just over 21% of all starts in Canada, a remarkable share for a province with roughly 12% of the national population. Nationally, CMHC reported 259,028 starts in 2025, up 5.6%, with Toronto down 31% and Vancouver down 3%.
Two details stand out:
- 70% of Alberta’s starts were multi-unit dwellings, the highest share on record (66% in 2024).
- About 90% of starts were in the Calgary and Edmonton metro areas. The record was concentrated in two cities and, within them, in apartment and attached product.
Why the record happened
The main driver was population growth. Alberta added almost half a million people between early 2023 and late 2025. Growth reached 4.7% in 2024 before slowing to 2.5% in 2025. Relative affordability compared with Ontario and British Columbia, strong employment and supportive municipal policy on density all pushed builders to launch projects at scale.
Purpose-built rental also benefited from federal financing programs and from investors looking for markets where rents could still support new construction. The result was a wave of multi-family projects started in 2024 and 2025, many of which will complete in 2026 and 2027.
Why records are not a strategy
Construction decisions are made in one market and delivered into another. A project approved during record migration may be completed when population growth has slowed by two thirds. ATB expects Alberta’s population to grow only about 1.5% in 2026 and housing starts to fall to roughly 45,000.
That is still about 33% above the ten-year average, so this is not a downturn. But the type of demand is changing. Early signs are already visible in Calgary, where in March 2026 apartment sales fell 28.8% year over year and apartment months of supply reached 4.62, while detached homes remained close to a seller’s market.
The supply-absorption gap
When completions arrive faster than buyers and tenants can absorb them, three things happen: incentives increase, sales periods lengthen and carrying costs rise. None of these show up in an annual housing starts headline, but all of them affect the actual return of a project.
The concentration risk
When 70% of new supply is one product type and 90% is in two metros, competition for the same buyer or tenant becomes intense. Projects that look similar on paper start competing on price.
How to read Alberta data before committing to a project
1. Look at segment data, not totals
Total starts tell you how busy the industry is. Segment-level months of supply, rents and absorption tell you whether your product will sell or lease on schedule.
2. Separate Calgary, Edmonton and secondary markets
Calgary and Edmonton differ in land costs, development charges, price levels and investor appetite. Smaller centres such as Airdrie, Cochrane or Red Deer follow their own cycles. A provincial average is not a feasibility input.
3. Model the delivery date, not the start date
Feasibility should test conditions at completion: expected competing supply, population growth forecasts and interest rate scenarios. A project that works with 2025 absorption may need different pricing or phasing in 2027.
4. Protect the margin through execution
When prices stop rising, cost discipline becomes the main source of return. Complete drawings before tender, a frozen design before site start and documented change control prevent the overruns that erase thin margins.
What a record year does to costs, labour and schedules
A construction boom does not only add units. It also competes for the same trades, materials and approval capacity. During a record year, framing crews, electricians and mechanical subcontractors are booked months ahead, and bids rise to reflect that demand. Municipal permitting and inspection departments face higher volumes, which can extend review times. Suppliers prioritise their largest customers, so smaller builders often wait longer for windows, doors and mechanical equipment.
When the cycle slows, these pressures do not disappear immediately. Contracts signed at peak prices still have to be delivered, and projects that started late in the boom may finish into a softer sales market with costs that were locked in at the top. This is why cost plans should be reviewed at every major milestone rather than only at budget approval. A quarterly review of committed costs, remaining contingency and expected revenue is a simple control that most overruns would have revealed early.
For owners and investors, the practical takeaway is to ask contractors and project managers for a schedule that reflects real trade availability, a procurement plan for long-lead items and a written process for approving changes. These documents cost very little to prepare and protect the margin when the market stops forgiving mistakes.
Where the opportunities are
A slowing condo segment does not mean the whole market is weak. Ground-oriented family housing, well-located rental with differentiated amenities, seniors housing and non-residential construction (industrial, institutional and infrastructure) remain active areas in Alberta. The developers who perform best in 2026 will be those who match product to demand rather than repeating what worked in 2024.
The bottom line
Alberta broke construction records in 2025 for good reasons, and the province remains one of the strongest construction markets in Canada. But growth does not make every project viable. Feasibility does: the right product, in the right city, delivered at the right time and on budget.
If you are planning a project in Alberta and want a second read on the numbers, explore my project management and feasibility services or contact me. You may also find useful my analysis of the Calgary housing market in 2026.
Frequently asked questions
How many housing starts did Alberta have in 2025?
54,858, a provincial record, up 15% from 2024 and just over 21% of all starts in Canada (ATB Financial, CMHC data).
Will Alberta housing starts fall in 2026?
ATB expects starts to fall to about 45,000 in 2026, still around 33% above the ten-year average.
What share of Alberta’s 2025 starts were apartments and multi-unit homes?
70%, the highest share on record.
Sources
- ATB Financial: Housing starts in Alberta, December 2025
- Storeys: CMHC 2025 housing starts
- REW: Calgary market analysis, March 2026 (CREB data)
- 230 views
- 0 Comment

Eros Belotti 01.

Eros belotti
Construction project manager with over 20 years of experience in Europe and the Canary Islands. Specialized in modular housing, container construction, real estate development and international project management. Founder of Reforma Vivienda Tenerife and Donkey Lab.