
//Alberta Real Estate 2026: Why Product Mix Beats Market Volume
Alberta Real Estate 2026: Why Product Mix Beats Market Volume
Tags : Alberta Housing MarketAltus GroupCalgary DevelopmentCanadian Housing 2026Construction Market Canadapre-sale exposureproduct mix strategyreal estate feasibilityrental housing Alberta
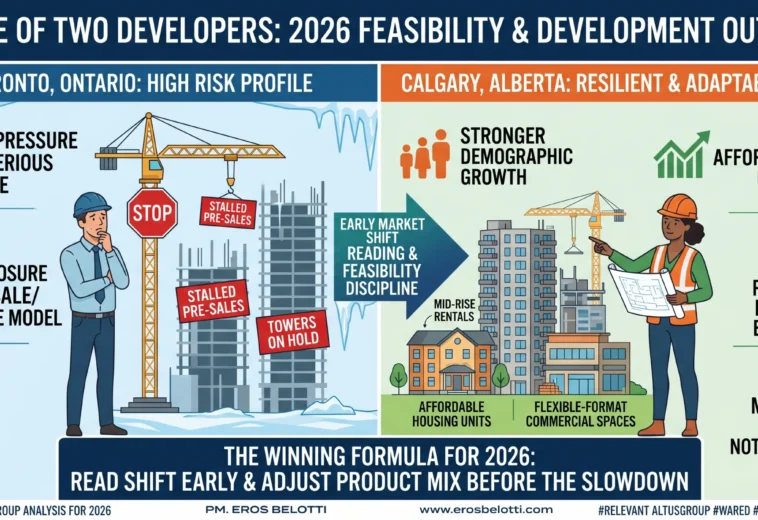
Imagine two developers in the same month of 2026, one in Toronto and one in Calgary. Both see the same national slowdown signal. Their risk profiles could not be more different. In Ontario and British Columbia, presales have stalled, high-rise projects are on hold and developer margins are under heavy pressure. Alberta is having a different conversation. It is cooling too, but from a more resilient base, and the outcome for each project depends less on the market as a whole and more on one decision: what product are you building, and for whom?
Two markets, two slowdowns
CMHC data show how differently Canada’s major markets moved in 2025. Housing starts in Toronto fell 31% and in Vancouver 3%, while Calgary and Edmonton both set records and Alberta accounted for over 21% of all starts in the country. The Toronto and Vancouver slowdowns are closely tied to the presale condominium model: when investors stop buying units off-plan, high-rise projects cannot reach the presale thresholds lenders require, and launches are postponed.
Alberta’s development model relies less on high-rise presales. A larger share of its construction is ground-oriented ownership housing and purpose-built rental, which is financed on a different basis. BILD Alberta reported that purpose-built rentals made up 34% of Alberta starts in Q1 2026.
Alberta is cooling, not immune
None of this means Alberta is immune. ATB Financial reported that Alberta’s housing starts in April 2026 fell to their lowest pace in two years, with year-to-date starts down 23% from 2025 and apartments hit hardest. Calgary’s resale market has softened, especially in apartments and row homes. CMHC expects Calgary starts to fall to about 22,000 in 2026 and rental vacancy to rise to around 5.9%.
But the base is stronger: population is still growing, affordability is better than in Ontario and British Columbia, and the economy is expected to lead the country in 2026 according to CMHC. A cooling market with solid fundamentals rewards good product choices rather than punishing everyone equally.
Why product mix matters more than volume
In a hot market, volume wins: the more units you deliver, the more you earn. In a selective market, the wrong product can lose money even when demand overall is healthy. In Calgary in March 2026, detached homes had 2.22 months of supply while apartments had 4.62. Two projects in the same city, in the same month, faced completely different absorption.
Exposed products
- Towers dependent on investor presale velocity.
- Small one-bedroom units aimed at investors rather than end users.
- Undifferentiated rental product in areas with rising vacancy.
More resilient products
- Family-oriented ground housing: townhomes, semi-detached and detached in well-located communities.
- Rental with a clear target tenant, good location and differentiated design.
- Affordable and below-market housing supported by public programs.
- Flexible formats: missing middle, secondary suites and units that can serve both owners and renters.
- Seniors housing and continuing care, backed by demographic demand and public capital.
How to choose the right product mix
1. Start from the end user
Who will live in these homes? Families, young professionals, seniors, students, newcomers? Their incomes, needs and preferences determine the right unit sizes, layouts and price points.
2. Map competing supply
List projects under construction and recently completed in the same submarket and product type. Rising completions in your segment are a warning sign.
3. Compare at least two configurations
Test alternative mixes on the same site: more family units versus more small units, ownership versus rental, phased versus single-phase. Compare revenue, cost, absorption and risk.
4. Check financing implications
Ownership projects may require presales; rental projects may qualify for different financing programs. The product mix shapes the capital stack.
5. Keep flexibility
Designs that allow units to be combined, rented or sold give developers options if market conditions change during construction.
Reading the shift early
The developers who will win in Alberta in 2026 are not necessarily the ones building the most units. They are the ones who read the market shift early and adjusted their product mix before the slowdown made it obvious. That is not luck. It is feasibility discipline applied before the market forces your hand.
Lessons from Ontario and British Columbia
The experience of Toronto and Vancouver offers a warning. Many projects launched during the low-rate years were designed primarily for investors: small units, high price per square foot and dependence on continued price growth. When rates rose and investor demand disappeared, those projects had few end-user buyers to fall back on. Alberta developers can avoid the same trap by designing for the people who will actually live in the buildings and by keeping their projects viable even without price appreciation.
Questions to ask before fixing the unit mix
- What is the months of supply for each unit type in this submarket today?
- How many similar units will complete nearby in the next 24 months?
- Which unit types have the shortest days on market and the lowest incentives?
- Can the design adapt if the mix needs to change before construction?
- Does the financing structure depend on presales of a specific unit type?
Clear answers to these questions usually point to a more balanced and more resilient mix than the one first imagined.
The bottom line
The real question is not whether Alberta is slowing down. It is what kind of product you are building and for which end user. Presale-dependent towers are exposed; rental, affordable and flexible-format projects face fewer headwinds. In 2026, product mix beats market volume.
If you are evaluating the product mix for a project in Alberta, see my feasibility services, read about missing middle housing in Alberta, or contact me.
Frequently asked questions
Why is Alberta’s housing market more resilient than Toronto’s?
Alberta has stronger population growth, better affordability and less dependence on the high-rise presale model that has stalled in Ontario and British Columbia.
Which housing products are most exposed in 2026?
Presale-dependent towers, investor-oriented small units and undifferentiated rental in areas with rising vacancy.
What share of Alberta starts were purpose-built rental?
BILD Alberta reported 34% of starts in Q1 2026, with 23,553 rental units under construction.
Sources
- Storeys: CMHC 2025 housing starts
- ATB Financial: Alberta housing starts, April 2026
- BILD Alberta: Quarterly Report Q1 2026
- CMHC: Summer update, 2026 Housing Market Outlook
- 198 views
- 1 Comment

Eros Belotti 01.

Eros belotti
Construction project manager with over 20 years of experience in Europe and the Canary Islands. Specialized in modular housing, container construction, real estate development and international project management. Founder of Reforma Vivienda Tenerife and Donkey Lab.
June 12, 2026 /
To add some context to this post:
The Altus Group data for 2026 makes one thing clear — Alberta’s relative resilience isn’t accidental. It’s the result of a different development culture: less speculation-driven, more grounded in end-user demand and realistic affordability margins.
The markets that are struggling right now built their pipeline around pre-sale velocity and high-rise absorption rates that made sense in a low-rate environment. That model is under pressure everywhere.
Alberta’s exposure to that model is structurally lower. That’s not a minor detail — it’s the core of the risk profile difference.
For developers, investors and project managers working in this market, the practical implication is straightforward: feasibility work that accounts for product mix, end-user profile and local absorption capacity is no longer optional. It’s the baseline.
If you’re evaluating a project in Alberta right now and want to stress-test your assumptions against current market conditions — that’s exactly the kind of work I do.