
//National Housing Starts Fall 5.2% in May 2026: What the Regional Data Means for Alberta
National Housing Starts Fall 5.2% in May 2026: What the Regional Data Means for Alberta
Tags : Alberta Real EstateCMHCconstruction feasibilityHousing Startsmarket dataPrairies real estateresidential construction Canada
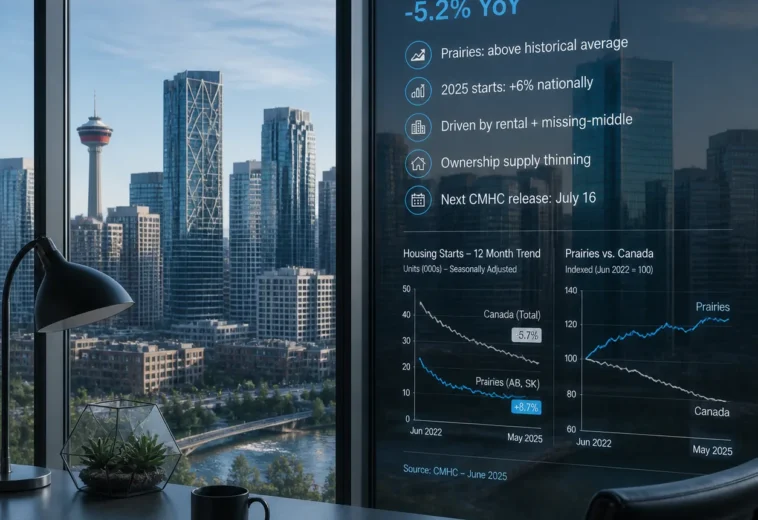
On June 15, 2026, CMHC reported that actual housing starts in Canadian centres with populations of 10,000 or more fell 5.2% year over year in May, to 22,633 units. Many readers will take that headline to mean residential construction is slowing everywhere at the same pace. It is not. The disaggregated data show sharp regional differences, and for developers in Calgary or Edmonton, the national number says very little about their own submarket.
This article breaks down the May 2026 data, explains where Alberta sits within it and shows how to use regional starts data properly in feasibility work.
The national picture
- Seasonally adjusted annual rate: 261,377 units in May, down 6% from April.
- Six-month trend: 258,010 units, up 0.5%, which CMHC described as virtually flat.
- Actual starts in centres of 10,000+: 22,633, down 5.2% from May 2025.
- Year to date: 93,644 starts, up 3% from 2025.
- Single-detached starts: flat year over year; all other units: down 6%.
CMHC’s deputy chief economist described the results as mixed and warned of weaker momentum for future supply, given the decline in approved units not yet started.
The regional story
The national year-to-date gain came mostly from British Columbia and Ontario. The Prairies moved the other way: year-to-date starts in the region fell 16%, and May starts dropped 9% year over year. Within the Prairies, Saskatchewan’s May starts rose 50%, while Alberta’s fell 15%.
In Alberta’s two largest cities:
- Calgary: 2,719 starts in May, down 11% year over year and 28% year to date, although the six-month trend rose 2% to 20,947.
- Edmonton: 1,942 starts, down 13% year over year and 14% year to date, with the trend up 2% to 18,152.
Alberta: declining, but from a record
Alberta’s decline needs context. The province set a record with 54,858 starts in 2025, and ATB Financial noted that even after recent declines, starts remained about 26% above the ten-year average in spring 2026. The slowdown is concentrated in multi-unit and rental construction, which drove the boom, while single-family construction is holding up better.
So Alberta does tell a different story from the national headline, but not the one often assumed. It is not outperforming in 2026 growth terms; it is normalising from an exceptional peak, while Ontario and British Columbia are partially recovering from very weak 2025 levels.
Why averages mislead
A national decline of 5.2% averages together markets moving in opposite directions: Toronto recovering from a 31% fall in 2025, Saskatchewan growing quickly and Calgary normalising after record years. For a developer, the relevant questions are local:
- Where is supply concentrated in my city and submarket?
- What type of product is being built: ownership or rental, detached or multi-unit?
- How many units completed recently or under construction will compete with mine?
Ownership thinning, rental absorbing completions
Across Canada, rental has become the dominant form of new construction. The Canadian Home Builders’ Association reported in April 2026 that ownership starts fell from about 70% of starts in 2021 to below 50%. In Alberta, purpose-built rental made up 34% of starts in Q1 2026 according to BILD Alberta, and many completions in 2026 and 2027 will be rental units. Meanwhile, new ownership supply, especially family-oriented product, is thinner.
For feasibility, that means two different baselines: rental projects face more competition from completions, while well-located ownership product may face less new supply than the headlines suggest.
How to use starts data in feasibility
Use the trend, not the month
Monthly starts swing with large projects. The six-month trend gives a better signal.
Go to city and product level
CMHC publishes data by census metropolitan area and by dwelling type. Use them.
Pair starts with completions and absorption
Starts show future supply; completions and absorption show current competition.
Watch the pipeline of approved units
CMHC highlighted the decline in approved units not yet started. Fewer approvals now mean less supply two to three years ahead, which can support projects timed for that window.
What this means for 2027 and beyond
If approvals and starts keep falling while population continues to grow, even at a slower pace, the gap between new supply and demand may widen again toward the end of the decade. CMHC’s own outlook forecasts national starts declining to about 211,900 by 2028. Developers who secure land and approvals now, while delaying construction until the numbers work, may be well positioned for the next upswing. Those who launch generic product into today’s completion wave face tougher conditions.
A practical tip
Build a simple table for your submarket with five lines updated monthly: starts by type, completions by type, units under construction, absorption or vacancy, and average price or rent. Twelve months of this table tell you more about your project’s risk than any national headline.
Ontario and British Columbia: recovery from a low base
The national year-to-date gain should also be read carefully. Toronto’s starts fell 31% in 2025 and Vancouver’s 3%, so part of the 2026 increase in those provinces is recovery from weak levels rather than strong new demand. For investors comparing provinces, growth rates can be misleading without the base year: a large percentage gain from a low base and a decline from a record peak can describe markets in very different positions.
The bottom line
A national decline does not tell a developer in Calgary or Edmonton what is happening in their submarket. It tells them what is happening on average, and averages hide the differences that matter. If your pro forma assumes the national trend applies locally, you are underwriting against the wrong baseline.
If you want help reading regional data for a specific project, see my feasibility services, read about the CMHC forecast for Alberta, or contact me. Are you seeing the same regional divergence in your market?
Frequently asked questions
Did housing starts fall in Canada in May 2026?
Actual starts in centres of 10,000+ fell 5.2% year over year to 22,633, while year-to-date starts were up 3%.
How did Alberta perform in May 2026?
Alberta’s May starts fell 15% year over year. Calgary was down 11% and Edmonton 13%, although both six-month trends rose 2%.
Are Alberta housing starts still high?
Yes, relative to history. After a record 2025, starts remained about 26% above the ten-year average in spring 2026, according to ATB Financial.
Sources
- CMHC: Housing starts and construction data, May 2026
- ATB Financial: Alberta housing starts, April 2026
- CHBA: Housing Market Index, Q1 2026
- BILD Alberta: Quarterly Report Q1 2026
- 135 views
- 1 Comment

Eros Belotti 01.

Eros belotti
Construction project manager with over 20 years of experience in Europe and the Canary Islands. Specialized in modular housing, container construction, real estate development and international project management. Founder of Reforma Vivienda Tenerife and Donkey Lab.
June 30, 2026 /
One detail worth adding: the gap between rental and ownership supply isn’t a temporary side effect of higher rates — it’s becoming a structural feature of how product gets financed and absorbed.
For anyone running feasibility on a project right now, the question isn’t “is the market slowing” — it’s “which absorption profile does this asset actually fit.” Misreading that distinction is where a lot of pro formas quietly go wrong.